United Parcel Service (NYSE: UPS) Navigates Strategic Shift and Dividend Concerns
Key points
- United Parcel Service (NYSE: UPS) is strategically moving away from low-margin Amazon deliveries, leading to a lowered price target of $107.00.
- The future of UPS's dividend, currently yielding 6.7%, is uncertain, with a payout freeze expected in 2026.
- Despite concerns over free cash flow coverage of dividends and rising costs, UPS anticipates over $91.00 billion in full-year revenue and $8.60 billion in adjusted operating profit.
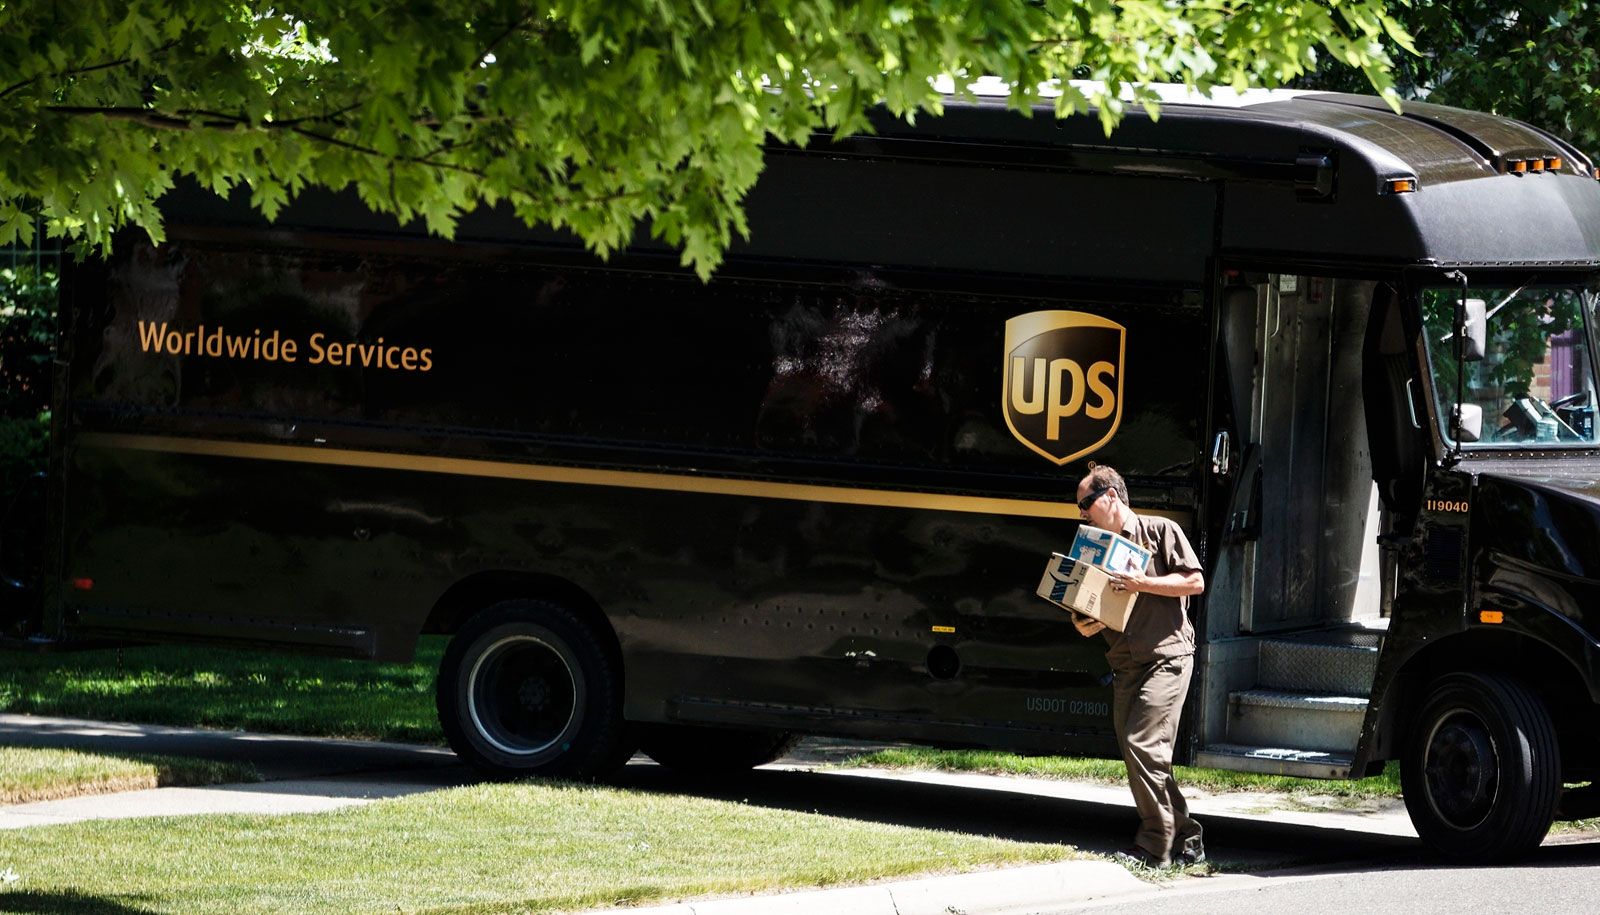
United Parcel Service (NYSE: UPS) is a package delivery company that is shifting away from high-volume, low-margin Amazon deliveries. Evercore ISI lowers its price target for UPS to $107.00 from $118.00. At $97.46 per share at the time of publication, the UPS stock trades about 9.8% below the new target.
UPS’s dividend yields 6.7% as of Oct. 16, but its future is uncertain. The company freezes its payout earlier in 2026, ending a 16-year streak of increases. As highlighted by The Motley Fool, UPS has made no definitive announcement about the UPS dividend’s future.
The dividend is a key concern because nearly all of UPS’s free cash flow—the cash left after business expenses and investments—goes toward the payout. A Seeking Alpha analysis rates the stock a sell, saying free cash flow barely covers its $5.40 billion dividend. It also points to debt and rising labor and diesel costs as risks for UPS.
Another Seeking Alpha analysis takes a more positive view. It reports double-digit growth in adjusted earnings per share and wider profit margins, helped by network changes and a shift toward higher-margin businesses such as healthcare. UPS forecasts more than $91.00 billion in full-year revenue and $8.60 billion in adjusted operating profit.
Read the rest, free
Pop in your email to read every article in full and search any company. It takes five seconds.
You'll get Gro's newsletter too. Leave any time in one click.